

1. Your 2027 dates, by birthday month
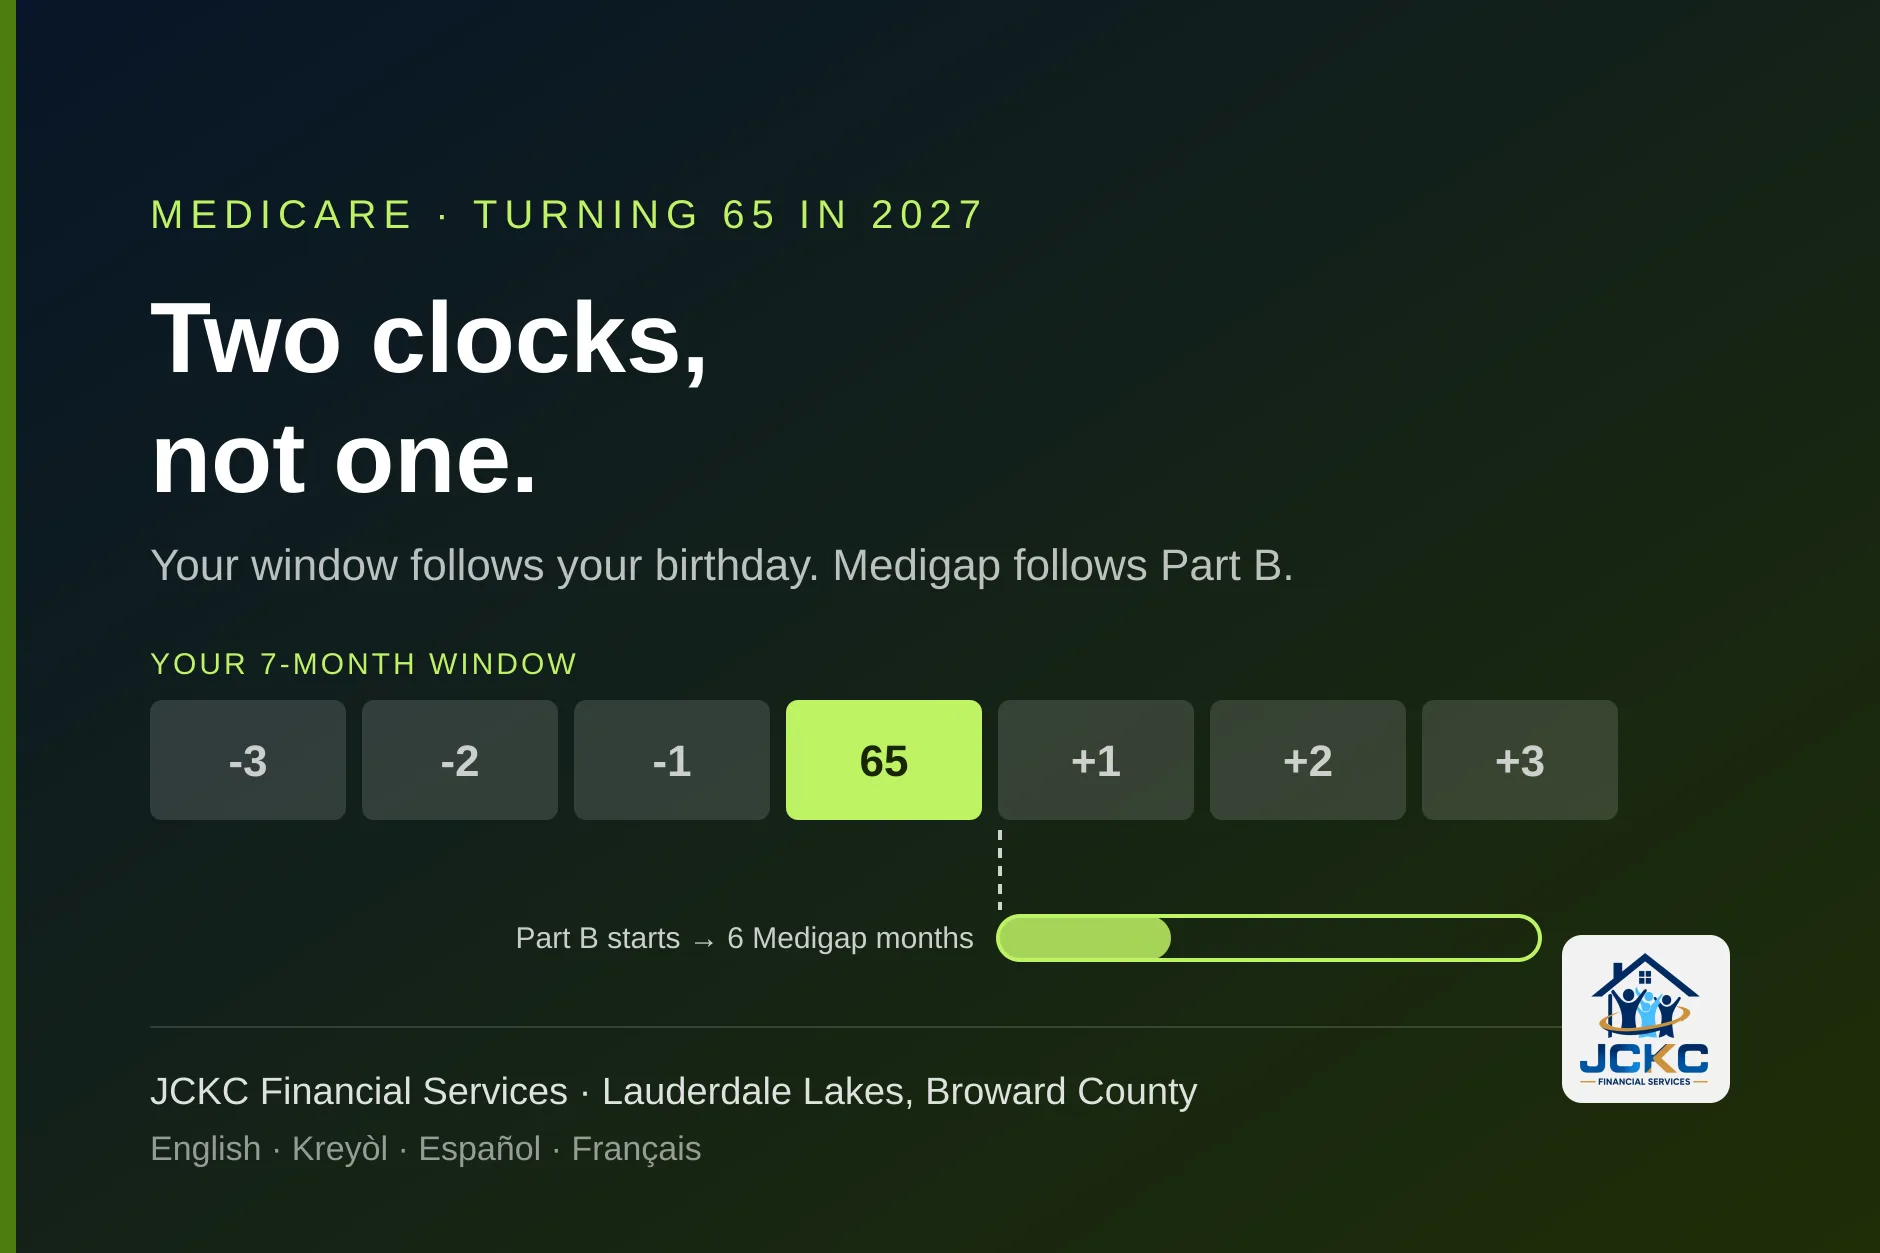
Your first chance to sign up is the Initial Enrollment Period. It lasts seven months: it starts three months before the month you turn 65, includes that month, and ends three months after it. Coverage always starts on the first of a month, and which first depends on when inside the window you sign up. Sign up before your birthday month and Part B starts in your birthday month. Sign up in your birthday month or the three months after and it starts the month after you sign up. Here is that rule worked out for every 2027 birthday:1
| Turning 65 in | Window opens | Window closes | Sign up by this date for Part B from the 1st of your birthday month | Medigap six months, if Part B starts in your birthday month |
|---|---|---|---|---|
| January | Oct 1, 2026 | Apr 30, 2027 | Dec 31, 2026 | Jan 1, 2027 → Jun 30, 2027 |
| February | Nov 1, 2026 | May 31, 2027 | Jan 31, 2027 | Feb 1, 2027 → Jul 31, 2027 |
| March | Dec 1, 2026 | Jun 30, 2027 | Feb 28, 2027 | Mar 1, 2027 → Aug 31, 2027 |
| April | Jan 1, 2027 | Jul 31, 2027 | Mar 31, 2027 | Apr 1, 2027 → Sep 30, 2027 |
| May | Feb 1, 2027 | Aug 31, 2027 | Apr 30, 2027 | May 1, 2027 → Oct 31, 2027 |
| June | Mar 1, 2027 | Sep 30, 2027 | May 31, 2027 | Jun 1, 2027 → Nov 30, 2027 |
| July | Apr 1, 2027 | Oct 31, 2027 | Jun 30, 2027 | Jul 1, 2027 → Dec 31, 2027 |
| August | May 1, 2027 | Nov 30, 2027 | Jul 31, 2027 | Aug 1, 2027 → Jan 31, 2028 |
| September | Jun 1, 2027 | Dec 31, 2027 | Aug 31, 2027 | Sep 1, 2027 → Feb 29, 2028 |
| October | Jul 1, 2027 | Jan 31, 2028 | Sep 30, 2027 | Oct 1, 2027 → Mar 31, 2028 |
| November | Aug 1, 2027 | Feb 29, 2028 | Oct 31, 2027 | Nov 1, 2027 → Apr 30, 2028 |
| December | Sep 1, 2027 | Mar 31, 2028 | Nov 30, 2027 | Dec 1, 2027 → May 31, 2028 |
Read your row twice, because three of its columns are dates people act on too late. The “sign up by” column is the one that avoids a gap: anyone who waits for the birthday itself has already moved their Part B start a month later. Premium-free Part A behaves a little differently. It starts in the month you turn 65 whenever you sign up inside the window, and if you sign up for it later it can reach back up to six months, though never to before the month you turned 65. Section 4 explains why that matters if you fund a Health Savings Account.1
If your birthday is on the 1st
Medicare.gov is specific about one thing: if your birthday falls on the first of the month, premium-free Part A starts the month before you turn 65. Someone born on March 1 gets Part A from February 1. Expect the rest of your dates to run early as well, and confirm the exact window with Social Security when you apply rather than reading it off the row for your birthday month.
2. Annual Enrollment is not your window
Almost all the Medicare advertising in South Florida this autumn is about Annual Enrollment, which runs from October 15 to December 7 and lets people who already have Medicare join, drop or switch plans for coverage starting January 1. If you are turning 65, that is not your window. Your window is the seven months in the table above. For a January, February or March 2027 birthday the two overlap this autumn, which is why people believe they have until December 7. A January birthday’s window opened on October 1, 2026, and it does not close on December 7.8
Inside your own window you can join a plan, not only sign up for Part A and Part B. To join a Medicare Advantage plan you need both Part A and Part B; to join a stand-alone drug plan, either one. If you ask to join before your Medicare starts, the plan starts the same day your Medicare does. If you ask after, it starts on the first of the month after the plan receives the request. So the clean order for most people is: Part A and Part B first, then the plan, both before the birthday month.8
3. Automatic, or through Social Security
Whether you have to do anything at all depends on one question: are you already receiving Social Security benefits?3
- Yes, and you started at least four months before you turn 65. You get Part A and Part B automatically. The welcome package with your Medicare card is mailed about three months before your coverage starts. If you are covered through a current employer and are thinking of delaying Part B, section 4 explains when that is safe.
- No, or you will start benefits later. Nothing happens on its own. You apply for Medicare through Social Security, not through Medicare and not through an insurance company. Medicare.gov describes the online application at ssa.gov, with a my Social Security account, as the easiest and fastest way. Medicare.gov lists signing up for Part A and Part B and applying for Social Security benefits as two separate options, so you can take Medicare without starting your retirement benefit.
- You already have Part A and are adding Part B later. That is also done with Social Security, online at SSA.gov or with form CMS-40B, and if you are using the job-based Special Enrollment Period you will also need a form showing the job-based coverage you had.
Missing the window without a reason that qualifies for a Special Enrollment Period leaves one route: the General Enrollment Period, January 1 to March 31 each year, with coverage starting the month after you sign up and, very likely, a penalty. It is a route back, not a plan.1
4. Working past 65: the test and the eight-month clock
A large part of Broward still works at 65, and the rule that protects you is narrower than people expect. You can usually wait to take Part B, with no penalty, only when all of this is true:2
- The coverage is a group health plan through a current job, yours or your spouse’s, available to everyone at the company.
- The employer has 20 or more employees. Below that, ask the employer in writing how its plan works with Medicare before you assume you can wait; if you do not sign up, the job-based insurance might not cover your costs.
- It is not COBRA, retiree coverage, a Marketplace plan or a self-employed plan. For those, Medicare.gov says to ask whether the coverage is employer group health plan coverage as the IRS defines it, and if it is not, to sign up at 65.
When the job or the coverage ends, whichever comes first, you have eight months to sign up for Part B without a penalty. The eight months start then, even if you take COBRA, and COBRA does not stretch them. To avoid a gap, Medicare.gov suggests signing up for Part B the month before you retire. If you sign up while you are still working, or within the first full month after the job coverage ends, you can ask for the Part B start to be delayed by up to three months so it lines up with the last day of the employer plan.1
If you have a Health Savings Account, stop six months early
Because Part A signed up after 65 can reach back up to six months, Medicare.gov tells people with an HSA that they and their employer should stop contributing six months before they retire or apply for Social Security benefits. Otherwise contributions made in the backdated months can become a tax problem. This is the point where your Medicare dates and your tax return are the same conversation, which is one reason we do both under one roof. The full rule set for this situation is in our guide to working past 65.4
5. The two penalties that last for life
Medicare has three late enrollment penalties, and two of them never end. They are not one-time fees. They are added to a monthly premium for as long as you have that coverage, which for most people means for life. Medicare’s own examples use 2026 amounts:5
| Part B | Part D (drug coverage) | |
|---|---|---|
| How it is counted | 10% for each full 12-month period you could have had Part B and did not | 1% for each month without Part D or other creditable drug coverage after you were first eligible, or any gap of 63 days or more |
| Percentage of what | The standard Part B premium | The national base beneficiary premium, $38.99 in 2026 |
| Medicare’s 2026 example | 2 full years late: $202.90 + $40.58 = $243.48, rounded to $243.50 a month | 14 months late: 14% of $38.99 = $5.46, rounded to $5.50 a month, on top of the plan premium |
| How long | As long as you have Part B | As long as you have Medicare drug coverage, even if you switch plans |
| What prevents it | Signing up in your window, a Special Enrollment Period, or a Medicare Savings Program | Creditable drug coverage with no gap of 63 days, or Extra Help |
The Part D penalty is the one people talk themselves into, because they take no medication at 65. If you have drug coverage through a job, it protects you only if it is creditable, and the plan must tell you in writing whether it is and sends that notice every year. Keep those letters: if a penalty is ever assessed in error, they are your evidence. The detail of all three penalties, including the Part A one that does end, is in our guide to late enrollment penalties.4
6. What 2027 costs: published and not yet published
A 2027 checklist has to be honest about which 2027 numbers exist. The Part B premium and deductible for 2027 do not exist yet. These are the 2026 figures, from the CMS announcement of November 14, 2025:6
| Item | 2026 (published) | 2027 |
|---|---|---|
| Standard Part B premium | $202.90 a month, up $17.90 from $185.00 in 2025 | Not yet published |
| Part B annual deductible | $283, up $26 from $257 | Not yet published |
| Part A premium | $0 for about 99% of people, who have 40 quarters of Medicare-covered work | Not yet published |
| Part A hospital deductible | $1,736 per benefit period | Not yet published |
When the 2027 Part B premium will be known
CMS had not published the 2027 Part B premium or deductible when this was written on October 30, 2026. The 2026 figures were released on November 14, 2025, so the 2027 announcement is normally expected around mid-November this year. Budget from the 2026 figure and expect it to move; we will update this page when CMS publishes, and not before.
Two other costs sit on top of that. If your income is high enough, an income-related surcharge is added to Part B and Part D, and it is set from a tax return two years old, which for someone retiring at 65 is usually the last full year of salary. If that describes you, our article on the life-changing-event request explains how to ask Social Security to use a newer year. And whatever plan you choose has its own premium, deductible and out-of-pocket limit, which is where the 2027 shelf in Broward comes in.
Turning 65 in 2027?
Your window may already be open. Let us put your dates, your job coverage and your drug list on one page.
7. The Medigap clock starts with Part B, not with your birthday
Medigap, also called Medicare Supplement Insurance, is a private policy that sits beside Original Medicare and pays some of the share Original Medicare leaves to you. There is one moment when no insurer can turn you down for it or charge you more because of your health: the Medigap Open Enrollment Period, the six months that begin on the first day of the month in which you are both 65 or older and signed up for Part B. Outside it there is no federal guarantee that a company will sell you a policy, and if one will, it may cost more because of past or present health problems.7
Notice what starts that clock. It is Part B, not your birthday. If you take Part B at 65, the six months run from your birthday month, which is the last column of the table above. If you delay Part B because you are still working, the six months wait for you and start when Part B does. The trap runs the other way too: Medicare.gov is explicit that the window starts once you sign up for Part B “even if you sign up for Part B while you still have employer coverage.” Someone who takes Part B early while still on a good employer plan can use up their only guaranteed Medigap window without ever needing it.7
Do not take Part B early by accident
If you are staying on a large employer’s group plan past 65, think before taking Part B “just in case”. It starts your premium, and it starts the one-time Medigap clock. Employer coverage often does a similar job to Medigap, so the six months can pass while you have nothing to use them for. We do not sell Medigap policies, so this is the rule rather than a pitch: know when your six months are before you choose your Part B date.7
8. Choose the structure, then the plan
Once Part A and Part B are settled, the real decision is structure: Original Medicare with a stand-alone drug plan, and possibly a Medigap policy, or a Medicare Advantage plan that takes over your Part A and Part B and usually includes drug coverage. We have set out that choice, and why in Florida one of the two doors is harder to walk back through, in our article on Medicare Advantage and Medigap, so we will not repeat it here. For the checklist, three points are enough:8
- Decide the structure before the plan. The structure constrains everything after it, including whether the Medigap window in section 7 matters to you at all.
- Bring your list, not your impressions. Every prescription with its dose, every doctor and hospital you will not give up. Those two lists decide a plan comparison far more than the premium does.
- You get one early correction. If you join a Medicare Advantage plan in your Initial Enrollment Period, you can change to another one, or go back to Original Medicare with or without a drug plan, within your first three months with Part A and Part B. After that, the ordinary yearly windows apply: Annual Enrollment from October 15 to December 7, and January 1 to March 31 for people already in an Advantage plan.
9. What is different in Broward
The rules are federal and identical everywhere. What changes in Broward is the shelf and the people choosing from it. Counted from the CMS files on our Broward County page:9
- 44 Medicare Advantage plans for 2027, down from 50 for 2026, of which 38 carry a $0 monthly premium, plus 62 Special Needs Plans counted separately. A $0 premium is not the same as a cheap plan; the out-of-pocket maximum and the drug deductible are where it shows.
- 380,230 people on Medicare in the county as of June 2026, and 64.8% of them in a Medicare Advantage or other health plan. Turning 65 here, you are joining a market where most of your neighbors chose Advantage, which is a fact about the market, not advice about you.
- The county line is not the network line. Many people here live in Broward and see a specialist in Miami-Dade or Palm Beach. Some networks run across the three counties; others stop at the boundary. Check each doctor by name, with the practice as well as the plan.
And language. A Medicare decision made in your second language is a decision made with less information than you deserve. From our office in Lauderdale Lakes we go through the letters, the cards and the plan documents in English, Haitian Creole, French or Spanish, and nothing is signed until you have understood it. For a one-page version of the order of decisions, see our short turning-65 guide.
10. The checklist: done, still to do, by when
This is the list we would hand you across the desk: what is already settled by your birthday, what you still have to do, and the dates by which to do it.
Already settled
- Your seven-month window, fixed by your birthday month (section 1).
- Whether you are enrolled automatically: only if you already draw Social Security, started at least four months before 65.
Still to do
- Find your row in the table and write the “sign up by” date in your calendar.
- Settle the work question in writing. If you or your spouse are working, ask the employer whether the plan is a group plan, how many employees the company has, and how it works with Medicare.
- Get your creditable coverage letter for drugs, and keep it.
- Stop HSA contributions six months before you plan to take Medicare or Social Security benefits, if you have an HSA.
- Apply through Social Security if you are not enrolled automatically.
- Choose the structure, then the plan, with your drug list and doctor list in hand.
- Mark your Medigap six months from the month Part B starts, whether or not you think you will use them.
- Check the 2027 Part B premium when CMS publishes it, expected around mid-November.
By when
| What | Deadline |
|---|---|
| Apply for Part A and Part B, so Part B starts the 1st of your birthday month | The last day of the month before your birthday month |
| Join a drug plan or Medicare Advantage plan, starting with your Medicare | Before your Medicare starts; at the latest, by the end of your window |
| Stop HSA contributions | Six months before you take Medicare or Social Security benefits |
| Part B after leaving a job with large-employer coverage | Within 8 months of the job or the coverage ending, whichever is first; ideally the month before |
| Change a Medicare Advantage plan chosen in your first window | Within your first 3 months with Part A and Part B |
| Buy Medigap with no health questions | Within 6 months of the first month you are 65 and have Part B |
11. Frequently asked questions
I turn 65 in February 2027. When can I sign up?
Your Initial Enrollment Period opens on November 1, 2026 and closes on May 31, 2027. If you sign up by January 31, 2027, Part B starts on February 1, the month you turn 65. Sign up in February or in the three months after and Part B starts on the first of the month after you sign up. Premium-free Part A starts in February either way, or in January if your birthday is February 1.
Is Annual Enrollment, October 15 to December 7, my deadline?
No, not if you are new to Medicare. Annual Enrollment is for people who already have Medicare and want to change plans for January. Your window is your own seven-month Initial Enrollment Period, built around your birthday month. If your birthday is early in 2027 the two overlap this autumn, which is why people mix them up.
Do I have to sign up, or does it happen automatically?
It is automatic only if you are already receiving Social Security benefits, and you started them at least four months before you turn 65. Then you get Part A and Part B and the card arrives about three months before coverage starts. Otherwise nothing happens until you apply through Social Security, and the easiest way is online at ssa.gov.
I am still working in Broward with insurance from my job. Do I need Part B at 65?
Not necessarily. If the coverage is a group health plan through your own or your spouse’s current job, and the employer has 20 or more employees, you can usually wait and sign up later without a penalty, during an eight-month Special Enrollment Period that starts when the job or the coverage ends, whichever comes first. COBRA and retiree coverage do not count, and COBRA does not pause the eight months.
How much is the Part B premium for 2027?
It had not been published when this was written on October 30, 2026. CMS announces the next year’s Part B premium and deductible in the autumn; the 2026 figures came out on November 14, 2025. For 2026 the standard premium is $202.90 a month and the deductible $283. We will not print a 2027 figure before CMS does.
How much is the late enrollment penalty?
For Part B, 10 percent of the standard premium for each full 12 months you could have had it and did not, added every month for as long as you have Part B. Medicare’s 2026 example: two years late makes the premium $243.50 instead of $202.90. For Part D, 1 percent of the national base beneficiary premium for each month without creditable drug coverage; in 2026, 14 months comes to $5.50 a month, added to the plan premium for as long as you have drug coverage.
When is my Medigap open enrollment?
The six months starting on the first day of the month in which you are both 65 or older and enrolled in Part B. It is tied to Part B, not to your birthday. If you take Part B at 65, it runs from your birthday month. If you delay Part B because you are still working, it starts later, when Part B starts. It happens once.
How many Medicare Advantage plans are there in Broward for 2027?
44 Medicare Advantage plans, down from 50 for 2026, of which 38 have a $0 monthly premium, plus 62 Special Needs Plans counted separately. Those counts come from the CMS 2027 landscape file and are kept current on our Broward County page. A count is not a recommendation: what decides it is your doctors, your prescriptions and your budget.
12. Sources
- Medicare.gov, When does Medicare coverage start? — the seven-month Initial Enrollment Period, Part A and Part B start dates, the birthday-on-the-1st rule for Part A, the six-month Part A lookback, the General Enrollment Period, the eight-month job-based Special Enrollment Period, COBRA, the three-month delayed Part B start and form CMS-40B. Read October 30, 2026.
- Medicare.gov, When can I sign up for Medicare? — the 20-employee test, the eight-month period starting when you stop working even with COBRA, signing up the month before you retire, and the extra form showing job-based coverage. Read October 30, 2026.
- Medicare.gov, How do I sign up for Medicare? — automatic enrollment when Social Security benefits start at least four months before 65, the card mailed three months before coverage, and applying through Social Security. Read October 30, 2026.
- Medicare.gov, Working past 65 — group coverage available to everyone at the company, the IRS definition question for other coverage, stopping HSA contributions six months before, and the creditable drug coverage notice. Read October 30, 2026.
- Medicare.gov, Avoid late enrollment penalties — the Part B and Part D penalty rules and the 2026 worked examples ($243.50 and $5.50 a month; national base beneficiary premium $38.99 in 2026). Read October 30, 2026.
- Centers for Medicare & Medicaid Services, 2026 Medicare Parts A & B Premiums and Deductibles, published November 14, 2025 — the $202.90 standard Part B premium, the $283 deductible, the $1,736 Part A deductible and the share of people with no Part A premium. Read October 30, 2026; no 2027 fact sheet had been published on that date.
- Medicare.gov, When can I buy a Medigap policy? — the six-month Medigap Open Enrollment Period starting with Part B, including when Part B is taken while employer coverage continues, and what happens after it. Read October 30, 2026.
- Medicare.gov, Joining a plan — joining a plan in the Initial Enrollment Period and when it starts, the three-month change after joining Medicare Advantage in that period, Open Enrollment from October 15 to December 7, and the January 1 to March 31 Medicare Advantage window. Read October 30, 2026.
- Centers for Medicare & Medicaid Services, CY2027 Medicare Advantage / Part D Landscape Source Files (published September 28, 2026) and Medicare Monthly Enrollment, June 2026 — the Broward County plan and enrollment counts, as counted and dated on our Broward County page (revised October 12, 2026).
For general information only. This article explains federal Medicare rules as Medicare.gov and the Centers for Medicare & Medicaid Services publish them. It is not tax or legal advice, and it is not a decision about your own enrollment: only Social Security can enroll you in Part A and Part B, and only an insurer can accept you into a plan. Dates in the calendar are worked out from the published rule; confirm yours when you apply. Premium figures are 2026 amounts unless stated otherwise. JCKC Financial Services is an independent insurance brokerage and tax practice in Lauderdale Lakes, Florida.