HMO or PPO in Broward County?
The short answer: Broward County has 44 Medicare Advantage plans for 2027, and 23 of them are HMOs. An HMO generally covers care only inside its network and usually asks for a referral to see a specialist. A PPO lets you use out-of-network providers for covered services at a higher cost and needs no referral. In Broward the average maximum out-of-pocket is $3,644 for an HMO and $6,308 for a PPO, so the freedom to go out of network has a price.1, 2, 4
Key takeaways
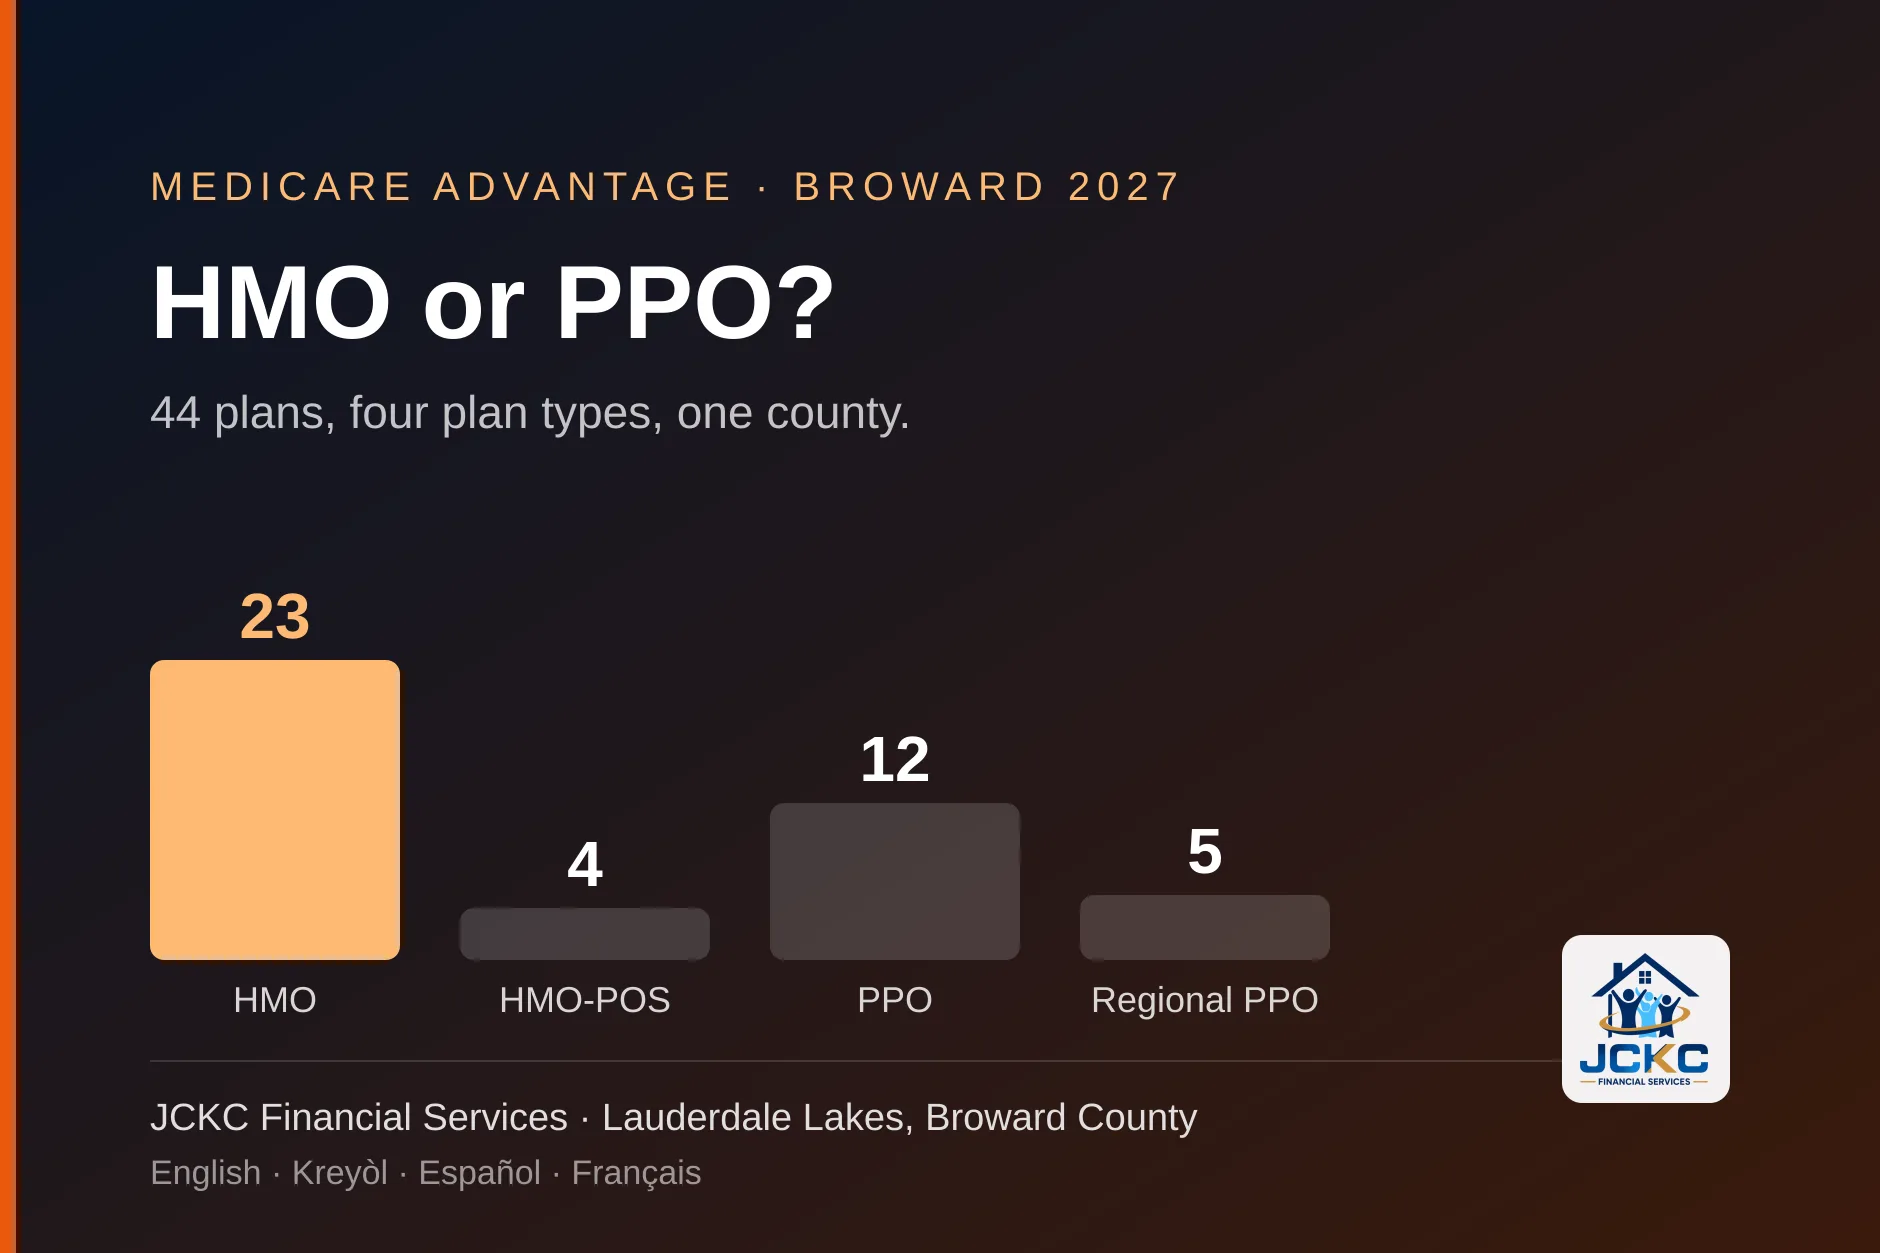
- 44 Medicare Advantage plans are on the CMS 2027 landscape for Broward: 23 HMO, 4 HMO-POS, 12 PPO and 5 Regional PPO.4
- An HMO means a network you stay inside, with exceptions for emergency care, out-of-area urgent care and temporary out-of-area dialysis, and in most cases a referral for specialists.1
- A PPO has no referral rule and no required primary care doctor, and you can use out-of-network providers for covered services, usually for more money.2
- All 23 HMOs and all 4 HMO-POS plans have a $0 monthly plan premium, against 10 of 12 PPOs and 1 of 5 Regional PPOs.4
- Choose the plan type for how you use care, then choose the plan for your doctors, your drugs and its yearly cap.
1. What are the four plan types in Broward?
Medicare Advantage, also called Part C, is run by private insurance companies that contract with Medicare. For Broward County, CMS lists 44 Medicare Advantage plans for 2027 in its plan-year landscape file, plus 62 Special Needs Plans that sit in a separate list.4 Every one of those plans belongs to one of four plan types, and the type decides what people feel most: which doctors you can see and what you pay when you step outside the network.
The four types in Broward are the HMO, the HMO with a point-of-service option (HMO-POS), the PPO and the Regional PPO. Medicare.gov describes the HMO and the PPO as the two main network designs.1, 2 An HMO-POS is an HMO that allows some out-of-network care for a higher copayment or coinsurance, and the Regional PPO is a PPO type that CMS reports on its own line in the landscape file.
Table 1 shows how the 44 plans divide. The counts are plans, not people, and one insurer can sell several plans of the same type.
| Plan type | Plans | Share of all plans | The network rule in one line |
|---|---|---|---|
| HMO | 23 | 52% | In-network care only, except emergency care and some care away from home; referral for most specialists |
| HMO-POS | 4 | 9% | HMO rules, with some services allowed out of network for a higher copayment or coinsurance |
| PPO | 12 | 27% | Out-of-network providers allowed for covered services, usually at a higher cost; no referrals |
| Regional PPO | 5 | 11% | A PPO type that CMS lists on its own line; confirm the rules in the plan documents |
Source: CMS CY2027 Medicare Advantage / Part D landscape, Broward County, 44 plans.4
The split is lopsided. HMOs and HMO-POS plans together are 27 of the 44 plans, or 61%, and the 17 PPO-type plans are the rest. That matters because Broward is a Medicare Advantage county: in June 2026, 246,276 of the 380,230 people with Medicare in the county, 64.8%, were enrolled in a Medicare Advantage or other health plan.7 A plan type that fits a small share of people badly still affects thousands of households.
The type also narrows your choice of insurer. The 23 HMOs come from 10 different insurers, while the 12 PPOs come from only 3: Humana (8), Florida Blue (3) and Aetna Medicare (1). If you want a PPO in Broward, you are choosing among very few insurers, so check that one of them also has your doctors.
2. How does an HMO work?
An HMO is a type of Medicare Advantage plan offered by a private insurance company. Medicare.gov says that with an HMO you generally must get your care and services from doctors, other health care providers and hospitals in the plan's network, with three exceptions: emergency care, out-of-area urgent care and temporary out-of-area dialysis.1 If you get health care outside the network in an HMO, you may have to pay the full cost.
That one rule produces most of the day-to-day differences. This is what an HMO asks of you, according to Medicare.gov:
- Choose a primary care doctor. In most HMOs you need to.
- Get a referral to see a specialist. In most cases a referral is required, although certain services, such as yearly mammogram screenings, do not need one.
- Follow the plan’s prior approval rules. When the plan requires prior approval for a service, it has to be in place before you get the service.
- Stay in the network. The only exceptions are emergency care, out-of-area urgent care and temporary out-of-area dialysis.
Medicare.gov also lists protections that apply to HMOs and PPOs alike. If your plan gives you prior approval for a treatment, the approval must be valid for as long as the treatment is medically necessary, and the plan cannot ask for additional approvals for it. If you are in treatment and switch to a new plan, you have at least 90 days before the new plan can ask for a new prior approval for that ongoing treatment.1, 2
In Broward, the HMO is the budget design. All 23 HMOs on the 2027 landscape have a $0 monthly plan premium, and the average maximum out-of-pocket is $3,644, with a range from $1,000 to $7,150.4 Of the 23, 21 include Part D drug coverage and 2 do not. That last number matters: Medicare.gov says that if you join an HMO that does not offer drug coverage, you cannot join a separate Medicare drug plan.1
If referrals are your main question, our short answer on whether 2027 Medicare Advantage HMOs in Broward need referrals goes through it in two minutes.
A referral is a process, not a denial
A referral requirement is a rule about order, not a limit on coverage. Your primary care doctor has to send you before the plan pays for the specialist. Before you enroll, ask each specialist’s office whether it accepts the HMO you are considering and how long new patients from that plan usually wait.
3. How does a PPO work?
A PPO is also a Medicare Advantage plan offered by a private insurance company. PPOs have networks of doctors, other providers and hospitals, and Medicare.gov says you pay less when you use providers and facilities in the plan's network. You can generally go to out-of-network providers for covered services, but you will usually pay more.2
These are the rules that differ from an HMO, according to Medicare.gov:
- No primary care doctor is required.
- No referral is needed to see a specialist.
- Out-of-network providers are allowed for covered services if they participate in Medicare or accept assignment, but you will usually pay more.
- Emergency and urgent care are always covered.
Medicare.gov adds that a PPO cannot charge you more than Original Medicare for certain services, such as chemotherapy, dialysis and skilled nursing facility care.2 That protection is easy to miss and it matters for anyone with a serious or long-running condition.
The trade shows up in the cost columns. In Broward the 12 PPOs have an average maximum out-of-pocket of $6,308, with a range from $3,900 to $9,250, and 10 of the 12 have a $0 monthly plan premium.4 Among the 8 PPOs that include Part D, the average monthly premium for the combined plan is $28.13.
Worth knowing
Out-of-network freedom in a PPO still has conditions. Medicare.gov tells PPO members to contact the plan before using an out-of-network provider, to make sure the service is medically necessary and covered. Freedom to leave the network is not freedom from the plan’s rules.
4. HMO-POS and Regional PPO: the in-between plans
Two smaller groups sit between the plain HMO and the plain PPO. HMO-POS plans follow HMO rules and add a point-of-service option: Medicare.gov says some HMOs are point-of-service plans that may allow you to get some services out of network for a higher copayment or coinsurance.1 Broward has 4 for 2027, up from 3 in 2026, sold by CarePlus (2) and Wellcare (2). All 4 have a $0 monthly premium and 4 include Part D. Their average maximum out-of-pocket is $2,963, the lowest of the four types, with a range from $750 to $5,000.4, 5
Regional PPO is the fourth type. CMS reports it on its own line, and in Broward it is the most expensive: 5 plans, only 1 with a $0 monthly premium, an average maximum out-of-pocket of $8,180 and a range from $6,700 to $9,850. They are sold by Humana (3) and UnitedHealthcare (2), and the 3 that include Part D average $107.67 a month for the combined plan.4
For most people the practical question is whether the safety valve in an HMO-POS is worth having. It can be: a point-of-service option may let you keep one out-of-network specialist or use care while traveling, at a higher copayment or coinsurance. It is not a PPO, though, and the HMO referral and prior approval rules still apply, so ask the plan which services the option covers.
A plan name is not a plan type
Plan names do not always say what the plan is. In the CMS file, “AARP Medicare Advantage from UHC FL-0031” is a Regional PPO and its name says nothing about it. Confirm the type in the plan documents or on the plan’s Medicare.gov listing before you enroll.
5. What do the Broward numbers show?
Table 2 puts the money side by side, using the plan-year 2027 landscape for Broward.4 “Maximum out-of-pocket” is the plan’s yearly cap on what you pay for covered services. It is a worst-case figure, not what you will pay in a typical year, and plans with a lower cap are not always the plans that cost less for the care you actually use.
| Plan type | Includes Part D | $0 monthly premium | Average max out-of-pocket | Range of max out-of-pocket |
|---|---|---|---|---|
| HMO | 21 / 23 | 23 / 23 | $3,644 | $1,000 – $7,150 |
| HMO-POS | 4 / 4 | 4 / 4 | $2,963 | $750 – $5,000 |
| PPO | 8 / 12 | 10 / 12 | $6,308 | $3,900 – $9,250 |
| Regional PPO | 3 / 5 | 1 / 5 | $8,180 | $6,700 – $9,850 |
Average of each plan's maximum out-of-pocket in the CMS CY2027 landscape for Broward County.4
Read the table in two directions. From HMO-POS to Regional PPO the average maximum out-of-pocket rises from $2,963 to $8,180, a difference of $5,217. That gap is the price of network freedom as the plans in this county price it. A PPO can still be the cheaper choice for someone whose doctors are all outside the HMO networks, because a low cap does not help if the care you need is not in the plan's network.
The ranges matter as much as the averages. Among HMOs the lowest maximum out-of-pocket is $1,000 and the highest is $7,150, so two HMOs can differ by as much as $6,150 in a worst-case year. PPOs run from $3,900 to $9,250. Across all 44 plans the average is $4,824. The type is a starting point, not a verdict: read the actual cap of the actual plan.
Not sure which type fits?
Bring your doctors and your prescriptions and we will compare the plan types with you, in English, French, Creole or Spanish.
6. Premiums and drug coverage by plan type
A $0 monthly premium is the norm in Broward for 2027: 38 of the 44 plans have one.4 That does not make the plans cost the same. Medicare.gov says HMOs and PPOs usually charge a premium in addition to the monthly Part B premium, and a plan can carry its costs elsewhere: copays, coinsurance, a drug deductible, a higher maximum out-of-pocket.1, 2 The Part B premium is paid to Medicare on top of whatever the plan charges.
Drug coverage is where plan type bites hardest. Medicare.gov says that if you join an HMO or a PPO that does not offer drug coverage, you cannot join a separate Medicare drug plan.1, 2 In Broward, 2 of the 23 HMOs and 4 of the 12 PPOs do not include Part D. If you take prescriptions, you are choosing a plan type and a drug plan in the same decision, and the wrong pick cannot be patched with a stand-alone drug plan.
For the plans that do include Part D, the landscape shows an average drug deductible of $310 for HMOs, $525 for HMO-POS, $700 for PPOs and $695 for Regional PPOs.4 Those are averages across plans with different tiers, so compare the deductible together with your own drug list. Our short answer on the 2027 Part D out-of-pocket cap explains how drug spending is capped once you pass the deductible.
Check the drug list, not only the type
Two plans of the same type can put the same drug on different tiers. Write down each prescription with its dose and look it up on each plan’s formulary before you compare anything else.
7. What changed since 2026?
Plan types are not fixed from year to year. Between the CY2026 and CY2027 landscape files, Broward lost 6 Medicare Advantage plans, from 50 to 44.4, 5 Table 3 shows where the change happened.
| Plan type | Plans in 2026 | Plans in 2027 | Change |
|---|---|---|---|
| HMO | 30 | 23 | -7 |
| HMO-POS | 3 | 4 | +1 |
| PPO | 12 | 12 | 0 |
| Regional PPO | 5 | 5 | 0 |
| All plans | 50 | 44 | -6 |
All of the net loss came from HMOs. They fell from 30 to 23, a drop of 7, while HMO-POS gained 1 and the PPO and Regional PPO counts did not move. Across all Medicare Advantage plans in the county the average maximum out-of-pocket moved from $4,697 in 2026 to $4,824 in 2027.4, 5
Fewer HMOs does not mean fewer choices for everyone. It does mean that if your current plan is one of the HMOs that left, you may be choosing a plan type again, not just an insurer. If you received a notice that your plan is ending, our guide to Medicare Advantage plan exits for 2027 explains the letter and your enrollment windows, and our guide to extra benefits covers what plans add on top of Medicare.
8. Which plan type fits you?
Plan type is really a decision about how you use care. Table 4 matches common situations to the type that usually fits, using the rules described above. It is a starting point for a conversation about your own situation, not a recommendation.
| If this describes you | Look first at | Why |
|---|---|---|
| You have a primary care doctor you trust and a short list of specialists who all sit in one network | HMO or HMO-POS | The rules are built around one network, and in Broward these types have the lowest average caps ($2,963 and $3,644).1, 4 |
| You see several specialists and do not want to ask for a referral each time | PPO | A PPO needs no referral and no primary care doctor.2 |
| You spend months outside Broward, or your doctors are in another state | PPO or HMO-POS | An HMO covers care away from home only for emergency care, out-of-area urgent care and temporary out-of-area dialysis. A PPO allows out-of-network providers at a higher cost, and an HMO-POS may allow some services out of network.1, 2 |
| The doctor you want to keep is not in any HMO network you checked | PPO | A PPO can cover out-of-network providers for covered services, usually for more money, so that doctor may stay in play.2 |
| You want the lowest worst-case year | HMO-POS or HMO | They have the lowest average maximum out-of-pocket in the county, but the range inside each type is wide, so read the specific cap.4 |
| You take prescriptions every month | Any type that includes Part D | You cannot add a separate drug plan to an HMO or PPO that does not offer drug coverage.1, 2 |
No row in Table 4 is a rule. The plan type is one of five things to compare, alongside your doctors, your drug list, the plan’s yearly cap and the extra benefits you would actually use.
Pick the plan type for how you use care, then pick the plan for your doctors and your drugs.
9. Your checklist before you enroll
Run this list before you enroll in anything. It takes about twenty minutes, and it is the difference between a plan that works in March and one that does not.
- List every doctor and facility, then check each one with the office. “Accepts Medicare” and “is in this plan’s network” are different statements, and a plan directory can be out of date.
- List every prescription with its dose, then look up the tier and cost of each one on the plan’s formulary.
- Find the plan type in the plan documents, not only in the plan’s name.
- Read the maximum out-of-pocket, not just the premium. A $0 premium with a high cap is a different product from a small premium with a low one.
- Ask about referrals and prior approval. In an HMO, find out who requests each one, you or your doctor’s office, and how long it takes.
- Think about travel. If you spend part of the year away from Broward, ask exactly what the plan covers there, beyond emergencies.
- Mind the dates. Open Enrollment runs October 15 to December 7, and a change you make then starts January 1. If you are already in a Medicare Advantage plan, the Medicare Advantage Open Enrollment Period from January 1 to March 31 lets you switch to another Medicare Advantage plan or return to Original Medicare.6
If you are comparing HMOs and PPOs for a specific city, our Broward County Medicare page shows the same county data next to the hospitals nearby, and our turning 65 checklist covers the first-time decision.
10. Next steps
Plan types are easy to compare once your doctors and drugs are on paper. We compare HMO, HMO-POS and PPO plans with you, in English, Spanish, French or Haitian Creole, and we explain the referral, network and cap rules of each plan before you decide. Our Medicare services page explains how a review works, and you can book a time on the booking page.
Not Sure How This Applies to You? Let’s Talk.
Bring your doctors and your prescription list. We will put the plan types side by side for your situation.
Book a Medicare review (954) 825-9923
JCKC Financial Services, 3692 W. Oakland Park Blvd., Lauderdale Lakes, FL 33311. Monday to Friday, 9 AM to 5 PM.
Simply put: an HMO keeps you in a network, asks for referrals and costs less at the cap in Broward; a PPO lets you go out of network and costs more at the cap; the right type is the one that matches the doctors you actually see and the drugs you actually take.
11. Frequently asked questions
What is the difference between an HMO and a PPO in Medicare Advantage?
An HMO generally covers care only from doctors, providers and hospitals in its network, asks you to choose a primary care doctor and, in most cases, requires a referral to see a specialist. A PPO also has a network, but you can usually use out-of-network providers for covered services at a higher cost, and it needs no primary care doctor and no referrals. Emergency care is covered in both.
Do I need a referral to see a specialist?
In most HMOs, yes, with exceptions such as yearly mammogram screenings. In a PPO, no. HMO-POS plans follow HMO rules for referrals. Ask the plan whether the specialist you want to see needs one before you book.
Can I see my doctor if they are out of network?
In a PPO you generally can, for covered services, if the provider participates in Medicare or accepts assignment, but you will usually pay more. In an HMO you generally cannot, except for emergency care, out-of-area urgent care and temporary out-of-area dialysis. An HMO-POS plan may allow some services out of network for a higher copayment or coinsurance.
Are there more HMOs or PPOs in Broward County for 2027?
HMOs. The CMS 2027 landscape lists 23 HMOs and 4 HMO-POS plans against 12 PPOs and 5 Regional PPOs, out of 44 Medicare Advantage plans in the county. HMO and HMO-POS plans together are 61% of the total.
Is a PPO always more expensive than an HMO?
Not on the monthly premium: 10 of the 12 Broward PPOs have a $0 monthly plan premium. The difference is in the yearly cap. The average maximum out-of-pocket is $6,308 for PPOs and $3,644 for HMOs, and the range inside each type is wide, so read the actual plan.
What is a Regional PPO?
It is a PPO type that CMS reports on its own line in the landscape file. Broward has 5 for 2027, sold by Humana (3) and UnitedHealthcare (2). They carry the highest average maximum out-of-pocket of the four types, $8,180.
When can I change from an HMO to a PPO, or the other way?
During Open Enrollment, October 15 to December 7, you can switch to another Medicare Advantage plan, with or without drug coverage, and the change starts January 1. If you are already in a Medicare Advantage plan, the Medicare Advantage Open Enrollment Period from January 1 to March 31 lets you switch to another Medicare Advantage plan or return to Original Medicare.
Do Special Needs Plans follow the same HMO and PPO rules?
Special Needs Plans are either HMO or PPO plan types, according to Medicare.gov, and they cover the same Part A and Part B benefits as other Medicare Advantage plans. Broward has 62 Special Needs Plans for 2027 in a separate list from the 44 plans in this article.
12. Sources
Current as of November 4, 2026. Plan counts and costs come from the CMS CY2027 and CY2026 landscape files for Broward County, and the plan rules come from Medicare.gov pages read on November 4, 2026.
- Health Maintenance Organizations (HMOs), Medicare.gov, read November 4, 2026.
- Preferred Provider Organizations (PPOs), Medicare.gov, read November 4, 2026.
- Special Needs Plans (SNP), Medicare.gov, read November 4, 2026.
- CY2027 Medicare Advantage / Part D Landscape Source Files (CY2027_Landscape_202609.csv, released September 28, 2026), Centers for Medicare & Medicaid Services. Broward County counts and averages as published on the county page of this site, read October 12, 2026.
- CY2026 Medicare Advantage / Part D Landscape Source Files (CY2026_Landscape_202603.csv, March 2026 refresh), Centers for Medicare & Medicaid Services, read October 12, 2026.
- Joining a plan: enrollment periods, Medicare.gov, read November 4, 2026.
- Medicare Monthly Enrollment (Broward County, June 2026), Centers for Medicare & Medicaid Services.
Disclaimer: JCKC Financial Services is a licensed independent insurance brokerage. This article is for general educational purposes only and is not tax, legal, medical, or financial advice, nor a substitute for guidance from a licensed professional about your specific situation. We are not connected with or endorsed by the United States government or the federal Medicare program. Plan counts, premiums, costs and availability change every year; call us at (954) 825-9923 for current specifics.